Searching for the best financial planner in Pakistan usually produces a confusing mix of bank advisors, insurance agents, stock brokers, and social media personalities — all using the same words. The label "financial planner" is not tightly regulated for individuals here, which means the burden of checking falls on you.
This guide gives you a practical checklist: what qualifications to look for, what questions to ask in the first meeting, how fees should work, and the warning signs that tell you to walk away.
Start With What "Best" Actually Means
The best financial planner is not the one with the biggest following or the most confident promises. It is the one whose process fits your situation, whose incentives are aligned with yours, and who can explain their recommendations in plain language. A top financial planner in Pakistan for a salaried professional in Lahore may be a different person from the right planner for a factory owner in Faisalabad.
1. Check Education and Certification
Look for formal finance education and a recognised professional qualification. In Pakistan, relevant credentials include finance degrees such as an MBA in Finance, certifications from the Institute of Financial Markets of Pakistan (IFMP), and international designations such as CFP®, CFA, or similar. Ask to see them. A certified financial planner or certified financial advisor should be comfortable telling you exactly where their certification comes from.
Certification alone does not make someone good, but a complete absence of formal training is a genuine risk when someone is advising on your life savings.
2. Understand How They Are Paid
This is the most important question and the one people forget to ask. There are three common models:
- Commission-based: The adviser is paid by the product provider. Advice is free to you but may lean toward products that pay more.
- Fee-based: You pay a clear, fixed fee for the plan. The adviser has no reason to prefer one product over another.
- Hybrid: A fee for planning plus commission on some products. Workable, as long as it is disclosed.
A professional financial planner in Pakistan should tell you, in writing, how they earn money from your engagement.
Get a Financial Fitness Scan™
A 60–90 minute diagnostic with Ameer Hamza that shows exactly where your finances stand and what to fix first — PKR 10,000.
See the Financial Fitness Scan™ →3. Ask About Their Process
A real planner has a defined process and can walk you through it. Ask: "What happens in the first meeting? What do I receive at the end? How do we review the plan?" If the answer is vague, or jumps straight to "let me show you this investment", you are talking to a salesperson.
A good process always starts with diagnosis — understanding your income, expenses, debts, assets, and goals — before any recommendation is made.
4. Look for Pakistan-Specific Knowledge
Ask how they account for inflation in their calculations, how they compare National Savings schemes with mutual funds, how filer status affects your returns, and how they approach Shariah-compliant options if that matters to you. Generic Western advice translated into Urdu is not financial planning for Pakistan.
5. Red Flags to Watch For
- Guaranteed returns or "double your money" promises.
- Pressure to decide in the same meeting.
- Recommending a product before understanding your full situation.
- Unwillingness to put fees or recommendations in writing.
- Asking you to transfer money to a personal account.
Any one of these is enough reason to stop.
Questions to Ask in Your First Meeting
- What are your qualifications, and where are they from?
- How are you paid, and will you disclose any commission?
- What will I receive in writing at the end of the engagement?
- How often will we review the plan, and what does that cost?
- Can you share how you worked with someone in a situation similar to mine?
Why Fixed-Scope, Fixed-Price Planning Works
I structure my own work as fixed-scope services with clear prices — from the Financial Fitness Scan™ to the Wealth Protection Plan™ — because it removes the conflict of interest. You know exactly what you are paying for and exactly what you will receive. The advice has no reason to push you toward any particular product.
Frequently Asked Questions
Is a certified financial planner better than an uncertified one?
Certification shows a baseline of knowledge and professional standards. It should be one of several filters, alongside process, fee transparency, and relevant experience.
How much does a financial planner cost in Pakistan?
Costs vary widely. Fixed-fee planning services can start around PKR 10,000 for a diagnostic session and rise for comprehensive wealth plans. What matters is clarity on what you receive for the fee.
Should I choose a planner in my own city?
Local knowledge helps, but most planning work today happens remotely. A financial planner based in Lahore can serve clients in Karachi, Islamabad, and Faisalabad effectively through online sessions.
Book a Free Financial Clarity Call
A 20-minute conversation with Ameer Hamza, financial planner in Pakistan, to find the right starting point for your money — no pitch, just clarity.
Book a Free Call →This article is general financial education, not personalised financial advice. Figures and returns are illustrative and not guaranteed; tax and scheme rules change, so confirm current rules before acting.
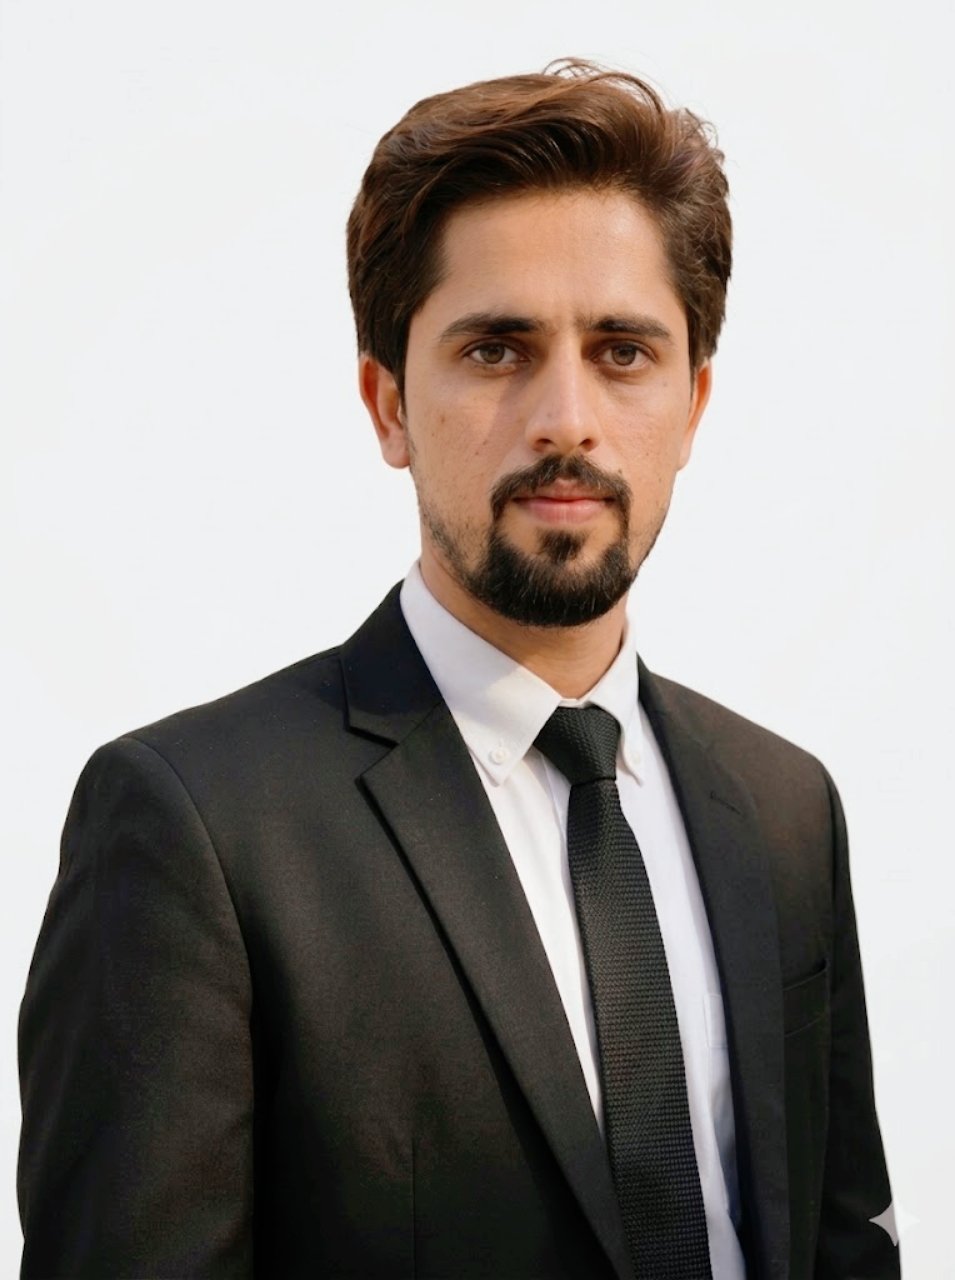
Financial planner and financial advisor in Lahore, Pakistan. MBA in Finance, Certified Financial Advisor (IFMP), founder of AssetBuild. About Ameer →
Related Reading
→ Financial Planner in Pakistan: What Does a Financial Planner Do?
→ Financial Advisor in Pakistan: Services, Benefits & Costs
→ Financial Consultant in Pakistan: What Services Do They Offer?